Cash Advance - No credit Check

Screenshots
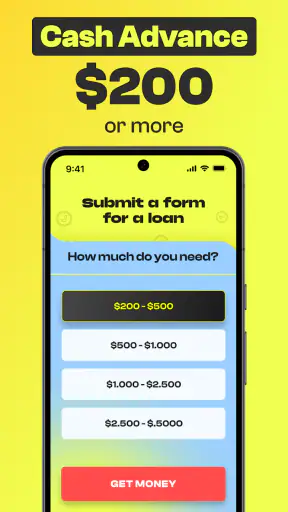
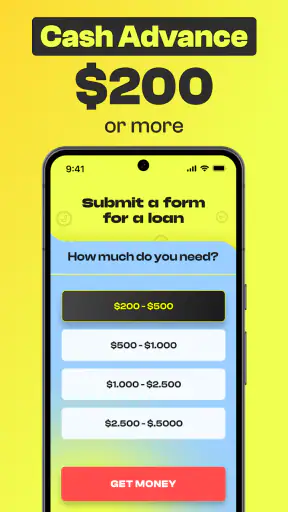
Details
- Rating
- 2.84K reviews
- Version
- 1.1.3
- Developer
- D.J. Advance App
Analysis by Norviv
When an unexpected bill lands before payday, a cash-advance app can look like a simple way to close the gap. My experience with Cash Advance - No credit Check is more cautious than that first impression: it is best understood as a starting point for exploring short-term cash options, not as a guaranteed emergency solution. The app sits in the finance category, is free to install, and is aimed at adults who want to investigate an advance without beginning with a traditional credit-check loan search.
The developer is D.J. Advance App, and the application has built a sizable audience, with more than half a million installs and a 4.7 average from roughly thirty-five thousand ratings. Those numbers suggest that many people find the basic experience approachable, but they should not be confused with a promise that every user will qualify, receive money instantly, or see the same offer. Finance apps deserve a slower reading of every screen, especially when the need for money makes it tempting to tap through quickly.
Where the experience usually gets stuck
I look at this section as a way to separate a slow or confusing screen from a real decision point. Before trying again, I note the exact step where progress stops and whether the message asks for an action or simply reports a result; that small distinction helps me avoid duplicate submissions and unnecessary changes to personal details.
The phrase “instant” needs a realistic interpretation
The app’s store positioning focuses on getting cash while waiting for payday, but “instant” should not be treated as a guaranteed arrival time. An application can be quick to open while eligibility checks, identity details, account review, or a separate provider’s decision still take time. In my view, this is the first important distinction: the app may help you begin a search quickly, yet it cannot remove the conditions attached to borrowing.
That matters when the expense is genuinely urgent. If a payment is due today, I would not rely on this app as the only plan. I would first contact the biller, ask whether a short extension is available, and check whether a bank transfer, employer advance, or trusted personal option is safer. A cash advance can solve a timing problem while creating a larger repayment problem, so speed is useful only when the total cost and repayment date are clear.
Application friction is not always a technical failure
People often assume that a stalled screen, an unavailable offer, or a request to review information means the app is broken. In a finance workflow, those events can also reflect eligibility rules, incomplete information, a mismatch between entered details and external records, or a result that simply is not available at that moment. The distinction is important because repeatedly submitting different answers will not improve a legitimate decision and may create confusion.
I recommend taking a screenshot of the exact message, without capturing sensitive information that you do not need to share, and reading the wording carefully. “Try again” points toward a temporary interruption; “not eligible” points toward a decision; and a request to correct details points toward setup. Treating all three as the same problem usually wastes time.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Read the handoff before accepting anything
A short-term borrowing journey may involve moving from the app into another page or service. Before continuing, I check whose name appears on the screen, what information is being requested, and whether the repayment amount is easy to identify. I also look for the due date, any fees, and the consequences of missing payment. If those details are difficult to find, I stop rather than assuming they will become clearer later.
The most useful habit is to separate “finding an offer” from “accepting an offer.” You can use the first stage to understand your options without committing immediately. A prominent button is not a reason to proceed; the actual repayment obligation is.
Why a no-credit-check promise can be misunderstood
The app’s name and store summary may appeal to people who worry about traditional credit checks. Still, no credit check does not mean no review at all, and it does not mean approval is automatic. A service may still ask for personal, employment, income, or account information before deciding whether it can present an option. I would never interpret the wording as permission to enter inaccurate information or as evidence that repayment terms will be inexpensive.
This is also where the app may not suit someone looking for a long-term financial product. If you need a larger amount, a predictable fixed schedule, or a lower-cost solution, a credit union, established bank, employer program, or nonprofit financial counselor may be a better place to start. The convenience of a short-term route is not the same as value over time.
Setup checks that prevent avoidable problems
Here I focus on the preparation that makes a first attempt easier to assess, from keeping information consistent to choosing a stable, private connection. I also consider what I would want to understand before entering sensitive details, so the next section can distinguish sensible preparation from granting access or sharing information without a clear reason.
Start with a clean, stable installation
Cash Advance - No credit Check supports Android devices using version 7.0 or later, which covers a broad range of phones. I would install it from the official app marketplace, keep the operating system reasonably current, and avoid modified installation files. A finance application is the wrong place to experiment with unofficial packages, especially when personal and financial information may be involved.
The current version is 1.1.3. If the app behaves oddly, I first check whether the marketplace offers an update and whether the phone has enough free storage. I also close other demanding apps, restart the device, and try again on a reliable connection. These are simple steps, but they distinguish a local device problem from an account or eligibility issue.
Prepare information before beginning
Starting the process while rushing can lead to spelling differences, incorrect contact details, or inconsistent income information. Before opening the application, I gather the details I expect to use and enter them consistently. I avoid switching between several versions of my name, address, or employment information simply because one attempt did not move forward.
This is a practical but often overlooked workflow: write down the non-sensitive details you intend to use, then enter them slowly. Do not keep a copy of passwords, security answers, or full account credentials in an exposed note. If a screen requests information that feels unrelated to the purpose of the application, pause and review the privacy and disclosure text before continuing.
Check the phone environment
Permissions and security settings can affect how an application behaves, but I would not grant every request automatically. If a permission appears, I ask whether it makes sense for the step I am performing. I also disable screen overlays, pause aggressive battery-saving restrictions for the app if necessary, and make sure the device’s date and time are set correctly. These checks can help with pages that fail to load or sessions that expire unexpectedly.
On a shared phone, I take extra care. I log out where possible, avoid saving financial details in the browser, and remove temporary information from the device afterward. A free download and an Everyone content rating describe accessibility, not financial safety. Adults should still treat the process as sensitive, and younger users should not be encouraged to borrow money simply because the app is easy to install.
Use one connection and one session
Switching repeatedly between mobile data, public Wi-Fi, and a home network can make a session look inconsistent. My preferred setup is a private, dependable connection, with a single attempt completed from one device. If the app returns to the beginning, I do not immediately submit the same request several times. I wait, reopen it once, and confirm whether an earlier attempt already exists.
Public networks deserve particular caution. Even when the app itself uses secure connections, I would rather complete a financial application on a trusted network than in a crowded place. I also avoid clicking unexpected messages that claim to accelerate approval. The safest troubleshooting path begins inside the installed application or the official marketplace, not through an unsolicited text or email.
Keep the cost question in front of you
Before accepting a cash advance, I calculate what will remain after repayment. If the advance is due shortly after payday, I subtract the repayment from rent, food, transport, utilities, and other fixed needs. This simple exercise reveals whether the app is solving a temporary shortage or moving the shortage into the next pay cycle.
I also compare the total repayment with alternatives. An overdraft, late fee, credit-card charge, or family loan may each have drawbacks, but the right comparison is the complete cost and the risk of falling behind. A cash advance that appears convenient can be the wrong choice if its repayment leaves no room for ordinary expenses.
Recovering when a workflow stops
When a workflow stops, I prefer a measured recovery over repeated taps or hurried reinstallation. I consider how to preserve any useful confirmation, identify the failing stage, and decide when another attempt is reasonable versus when it is better to stop and seek a different route.
When the app closes or loops
If the application closes unexpectedly, I restart the phone before reinstalling anything. Reinstalling can remove local session information and may make it harder to tell whether an earlier attempt was recorded. I then check for an update, confirm the connection, and reopen the app. If the same screen repeats, I stop submitting information and record the wording of the error.
Clearing temporary app data can sometimes resolve a corrupted local session, but I treat that as a later step because it may remove unsaved progress. I never clear data while an important confirmation is still visible unless I have noted what I need. If the application offers an in-app support route, I use the exact error text and the device’s basic software details rather than sending a vague message such as “it does not work.”
When verification does not progress
A verification step can fail because details are difficult to read, the camera cannot focus, the lighting is poor, or the information entered does not match the document. I use even lighting, clean the camera lens, remove glare, and make sure the entire document is visible if the screen requests it. I do not edit or obscure required information, and I do not send identity documents through unofficial support accounts.
If the same verification attempt fails more than once, trying random variations is a poor strategy. I review each field carefully and look for a legitimate correction path. If the information is correct but the process still stops, I treat that as a service-side or eligibility issue rather than something I can fix by guessing.
When no offer appears
No offer is not the same as a broken button. An application can be functioning normally while returning no suitable option for a particular person, location, income pattern, or timing. I would not uninstall and reinstall repeatedly, enter a different income figure, or create multiple profiles to force a result. Those actions can make personal records harder to reconcile and do not create affordability.
This is one of the most important trade-offs with a cash-advance app: convenience is conditional. The app may be useful for quickly checking whether a route is available, but it cannot guarantee that the route will exist. If the need is immediate and the result is unavailable, I move to a backup plan instead of spending the whole day refreshing the same screen.
When the app sends you elsewhere
Some users may be unsure whether they are still dealing with the application after a page opens outside it. I check the name of the service, the address shown by the operating system or browser, and the disclosures before entering anything else. I close pages that ask for passwords, security codes, or payment information in a way that does not match the stated purpose. I also avoid approving a transaction merely because the page uses urgent language.
If a confirmation arrives, I save the reference details without storing unnecessary sensitive information. I read the repayment schedule immediately and set a personal reminder before the due date. A calendar reminder is not a feature claim about the app; it is a safeguard I add myself because relying on memory is risky when several bills are due together.
When the app is not the cause
Not every failed step originates in the app, so I look at the wider chain: the phone, connection, account details, and any outside service involved. This section helps me decide which part I can safely check myself and when an unavailable result is a reason to change plans rather than keep troubleshooting.
Bank and account issues can look like app errors
A cash-advance process may depend on information outside the app. A bank account restriction, outdated account details, a name mismatch, or a delayed transaction can prevent progress even when the interface loads normally. I check the account separately through the bank’s official application or website, never through a link in an unexpected message, and confirm that ordinary transfers are working.
If the bank shows a pending or reversed transaction, I wait for that issue to be explained before trying another advance. Taking a second advance to cover a first one is a particularly dangerous reaction to uncertainty. The correct next step is to identify whether money was actually sent, whether it was returned, and what obligation remains.
Eligibility is different from device compatibility
A phone can meet the minimum operating-system requirement while the user still does not receive an offer. Technical compatibility only means the software can run; it says nothing about financial eligibility, location, account history, income, or the terms that may be available. Keeping those concepts separate prevents a great deal of unnecessary troubleshooting.
In practical terms, I use the app as a screening tool rather than a promise. If it opens, accepts information, and clearly explains the next step, it may have done its job even if the result is not approval. That is frustrating when money is needed, but it is more honest than treating every unavailable result as a defect.
Privacy and security deserve their own decision
Before using any finance app, I consider whether I am comfortable sharing the requested information and whether the purpose is clear. I read the privacy notices and permission prompts, use a strong device lock, and avoid entering details while someone else can watch the screen. I also watch for impersonation: a legitimate-looking name in a message is not proof that the sender is connected to D.J. Advance App.
If I decide the information request is too intrusive or the terms are too unclear, I leave. There is no advantage in completing a borrowing process that I do not understand. The free price removes an installation charge, but it does not remove the need to examine the financial arrangement that may follow.
Who should use it, and who should skip it
This app makes the most sense for someone who needs to explore a small, short-term cash option, understands that availability is conditional, and can repay without sacrificing essential expenses. It may also suit a person who wants a faster first look than visiting several traditional lenders individually, provided they compare the final terms carefully.
I would skip it if the expense is ongoing, the repayment would consume the next paycheck, or the user is already juggling several advances, overdrafts, or overdue bills. It is also a poor fit for anyone who wants guaranteed approval, a long repayment period, or a transparent substitute for financial counseling. In those situations, a bank, credit union, employer resource, or nonprofit adviser may offer a more suitable conversation.
My practical verdict after using it
Cash Advance - No credit Check is approachable and easy to try, which explains why it has attracted strong user attention. Its free availability, broad Android compatibility, and clear focus on payday gaps make it convenient for an initial search. I appreciate that a user can begin investigating a short-term option without treating a traditional loan application as the only route.
My reservation is not about the installation itself; it is about the gap between quick access and affordable borrowing. The app cannot guarantee an offer, instant delivery, or a result that fits every budget. Its value depends on how carefully the user reads the handoff, checks the complete repayment obligation, and keeps a backup plan ready.
For an everyday example, imagine a utility bill arriving two days before payday. I would open the app only after checking whether the provider offers an extension, then review any available option against the amount left after rent and groceries. If repayment would leave the next paycheck short, I would decline and negotiate the bill instead. That workflow uses the app as one source of information rather than allowing urgency to make the decision.
The application is rated for Everyone and was released on December 5, 2022, but those details should not be mistaken for a recommendation for every financial situation. My final view is straightforward: use it as a cautious comparison and screening tool, never as a guaranteed emergency fund. If the terms are clear, the repayment is genuinely manageable, and the process behaves normally, it may be worth considering. If the cost, provider, timing, or data request remains unclear, closing the app is the financially safer choice.
Frequently Asked Questions
01What is Cash Advance - No Credit Check, and how does it work?
Cash Advance - No Credit Check is a financial app designed to connect users with potential short-term cash advance or loan offers. After entering personal and financial information, the app may evaluate your details and present available options from third-party lenders or service providers. Approval, loan amounts, interest rates, fees, and repayment schedules are not guaranteed and depend on the provider’s requirements.
02Can I really get a cash advance without a credit check?
The phrase “no credit check” should be understood carefully. Some providers in the app’s network may use alternative information instead of relying only on a traditional credit score, while others may still perform a credit inquiry or review your banking and income details. Approval is never automatic, and users should read the lender’s terms to understand which checks may be performed before accepting an offer.
03How much does a cash advance through the app cost?
The total cost can vary significantly depending on the lender or service provider you are matched with. Possible charges may include interest, origination fees, subscription fees, late-payment penalties, expedited-funding fees, or other service costs. Before agreeing, carefully compare the annual percentage rate, total repayment amount, due date, and all applicable fees rather than focusing only on the amount received.
04What information is required to use Cash Advance - No Credit Check?
Users may be asked to provide identifying details, contact information, employment or income information, banking details, and permission to verify certain financial data. This information can be sensitive, so review the app’s privacy policy and the identity of any third-party provider receiving your data. Avoid submitting information through unofficial versions of the app or suspicious links.
05Is Cash Advance - No Credit Check safe and suitable for emergencies?
The app may be useful for comparing potential short-term borrowing options, but it should not be treated as guaranteed emergency funding. Short-term advances can be expensive and may create financial pressure if repayment is due before your next paycheck. Check the provider’s reputation, licensing where applicable, privacy practices, and complete loan agreement. Never pay an upfront fee to guarantee approval.


